A new bond from Zanaco may sound like a story for bankers and pension funds. But its real significance could eventually be felt by businesses looking for money to buy equipment, expand farms, install solar power or build new infrastructure.
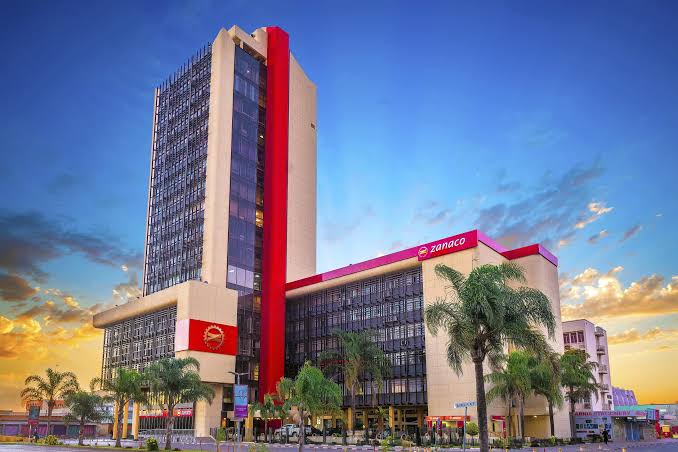
Zanaco has announced a US$100 million Medium-Term Note Programme, starting with a planned US$50 million sustainability bond.
It is the first sustainability bond issued by a Zambian bank, according to the Lusaka Securities Exchange.
The idea is relatively simple: investors provide Zanaco with capital, and the money raised is intended to support projects with defined environmental and social benefits.
That includes areas such as renewable energy, climate-smart agriculture, energy efficiency, affordable housing, healthcare, education and financial inclusion.
For Zambian businesses, the interesting question is not really what a sustainability bond is.
It is whether it creates another source of money for productive investment.
So, what changes for a business?
Imagine a farming company that wants to invest in irrigation.
The investment could improve production for years, but the equipment requires substantial money upfront. The same applies to a manufacturer wanting to install solar power, a property developer building more energy-efficient housing, or an SME investing in equipment that reduces its energy costs.
Traditionally, such businesses might rely on conventional bank loans, shareholder capital or retained earnings.
Sustainability finance introduces another possibility.
Capital raised through the bond can be channelled into qualifying projects, potentially expanding the amount of financing available for businesses whose activities meet the relevant sustainability criteria.
Zanaco's existing green-finance framework already identifies areas including renewable energy, resource efficiency, green buildings, climate-smart agriculture, aquaculture, forestry and waste management.
But this is not a cheap-money announcement
There is an important caveat.
The US$50 million does not mean every SME will suddenly be able to borrow at lower interest rates.
Businesses will still have to qualify for financing, and projects will need to meet the requirements attached to sustainability funding.
For some companies, therefore, the immediate impact may be limited.
The bigger opportunity is the possibility of more capital being directed towards particular types of investment.
Agriculture could be one of the biggest beneficiaries
Agriculture provides a good example of why this matters.
Irrigation, storage, solar-powered equipment, efficient processing and other climate-smart investments can make businesses more productive and resilient. But many require significant capital before they start generating returns.
If sustainable finance helps fund those investments, the benefits can extend beyond an individual company.
A better irrigation system can increase production. Better storage can reduce losses. More efficient processing can create additional value from agricultural output.
That is where financial-market developments begin to connect with the real economy.
And SMEs should pay attention
For a small business, the language of sustainable finance can sometimes sound distant.
But the underlying question is familiar: Where can I get the money to grow?
A sustainability-finance pipeline could become relevant to SMEs investing in energy efficiency, renewable energy, climate-smart agriculture and other qualifying activities.
Zanaco says the programme is intended to support entrepreneurs and SMEs alongside farmers and communities requiring social infrastructure.
The eventual impact, however, will depend on the financing terms, eligibility requirements and how effectively the money reaches viable projects.
Why the bond matters beyond Zanaco
There is also a bigger story developing in Zambia's financial markets.
The country needs capital for productive investment, while investors — particularly institutional investors — need opportunities to deploy long-term funds.
A sustainability bond attempts to connect those two needs.
Instead of capital simply moving through the financial system, it is tied to a defined set of environmental and social investments.
The Lusaka Securities Exchange has described the transaction as a new chapter for Zambia's capital markets and indicated that it wants to work with stakeholders to develop a pipeline of future thematic bonds.
That could eventually lead to more specialised financing instruments for sectors such as energy, agriculture, housing and infrastructure.
The real test starts after the headline
US$100 million makes for an impressive headline.
But the more important story will be what happens after the money is raised.
Which businesses receive financing?
What are the interest rates and repayment periods?
How many SMEs can actually access it?
How much goes into productive investment rather than simply refinancing existing obligations?
And does the financing generate measurable economic activity?
Those questions will determine whether sustainability finance becomes more than a new label in Zambia's banking sector.
For businesses, the message for now is straightforward: a new pool of capital is being created around projects that meet sustainability criteria.
The opportunity will be in understanding the criteria — and positioning viable projects to qualify.
For Zambia's financial system, meanwhile, Zanaco's bond marks an important shift: sustainability is increasingly becoming not just a development concept, but a way of organising and mobilising capital.